The problem you told us about
Until now, a borrower could hold only one loan on the platform. To take another loan, they had to fully repay and close their existing loan first, which meant repeat borrowers had to go through the borrowing process elsewhere.
What’s changed
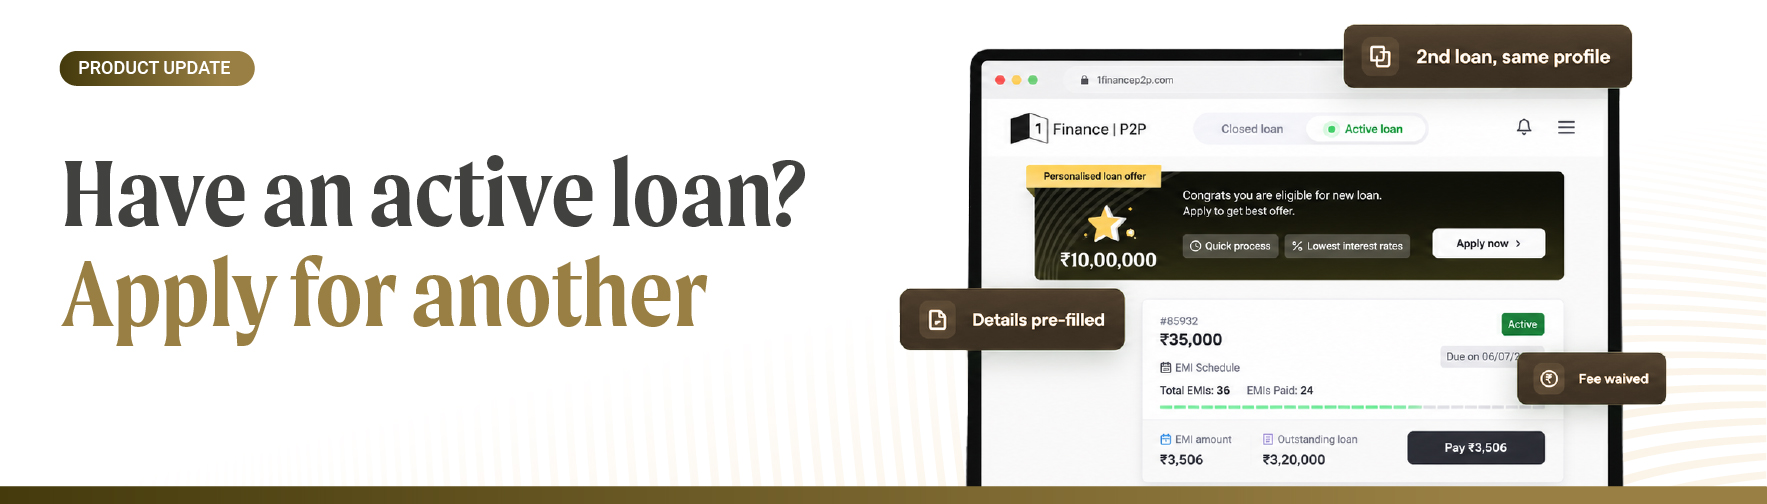
Eligible existing borrowers can now apply for an additional loan directly through their existing profile.
If the current loan is active, the borrower must have paid at least 25% of the EMIs on their most recent active loan before applying for another loan. This threshold is subject to confirmation by Credit Underwriting.
The new application can reuse information already available on the borrower profile, including PAN, employment and salary details, registered email and bank account information. Borrowers only need to re verify information that is outdated or requires fresh verification.
The total outstanding principal across all live loans will be subject to an overall ₹10,00,000 exposure cap. The maximum amount available for a new loan will depend on the existing outstanding principal and the applicable underwriting assessment.
Based on the borrowers updated financial information, credit history and repayment pattern with 1 Finance P2P, they may be eligible for an assessment fee waiver. If eligible, the waiver will be applied automatically by the BRE.
For repeat applications, several details can be reused or skipped where applicable. PAN may be pre filled, and an existing CKYC record may be reused if it is still considered valid under the applicable risk based validity criteria. If the information no longer meets these criteria, the required details may need to be fetched or provided again. Company and salary details remain editable, the existing bank account can be pre-selected where applicable, email verification can be skipped if the registered email remains valid, and penny drop can be skipped when the same bank account is selected, subject to applicable checks.
However, a new e-NACH mandate is required for every new loan, and new KFS and Loan Agreement documents will be generated for each additional loan.
In Phase 2, qualifying repeat borrowers may receive pre-approved loan offers with a sanctioned amount without completing a fresh loan application. The exact eligibility criteria, tenure and sanctioned amount calculation will be finalised before launch.
Why is this important
Repeat borrowers no longer have to start their borrowing journey from scratch every time they need another loan.
The feature makes repeat borrowing simpler by reusing existing customer information and repayment history, while continuing to apply underwriting checks and exposure controls.
The ₹10 lakh exposure cap limits the total outstanding principal across live loans. A borrower’s maximum new loan amount is calculated as:
₹10,00,000 minus outstanding principal across existing live loans
The additional loan will still be subject to underwriting and other applicable eligibility criteria.
The feature is being introduced in two phases:
Phase 1: Additional loan eligibility, application journey, reuse of existing information, exposure limit calculation, assessment fee waiver and applicable underwriting and verification checks.
Phase 2: Pre-approved offers for qualifying borrowers, including active and closed loan scenarios, with the sanctioned amount and tenure based on rules approved by Business and Credit Underwriting.
Where to find it
Eligible existing borrowers can access the additional loan application through their existing 1 Finance P2P profile.
The availability of the feature and the loan amount will depend on the borrower’s loan status, repayment history, underwriting assessment and applicable exposure limits.
Note: The 25% EMI threshold, 12-month recency window, definition of on time repayment, pre-approved offer tenure, EMI Eligible calculation and certain loan state treatments are still subject to final Business and Credit Underwriting confirmation.